 Member
Cameron
MemberForum Replies Created
-

Hello John!
Conventional will not allow to close an investment property as a STR, BUT-
We can definitely assist you closing an STR going DSCR.
theNONI™ ( Non-Owner, No Income ) is the #1 DSCR product out there!Let me know if you have any questions!
Best,
-
Cameron
MemberJuly 11, 2023 at 8:58 pm in reply to: DOWN PAYMENT ASSISTANCE FIRST-TIME HOMEBUYER WITH THE LENDER CAMERON LeCLAIREveryone,
I wanted to try to give a bigger explanation on why we do not do 100% FHA in Washington, Kentucky, & Massachusetts.I spoke with my Management & was advised that the state regulations & requirements for those 3 states are too difficult to work with regarding the 2nd Lien for that 3.5% .
So theLender chose not to continue with financing in these states for that reason.
Please let me know if you have any further questions regarding this.
Thank You! -
Hey Gus,
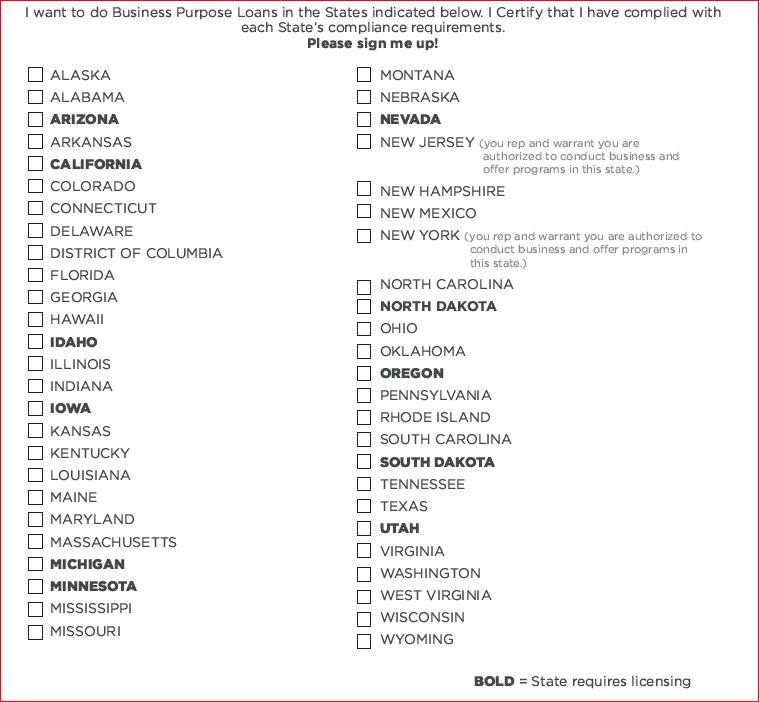
If you are inquiring about rental properties, We can do NO DOC DSCR in ALL 50 States.

-
Cameron
MemberJuly 11, 2023 at 4:29 pm in reply to: DOWN PAYMENT ASSISTANCE FIRST-TIME HOMEBUYER WITH THE LENDER CAMERON LeCLAIRFollow up-
We do not currently offer any Special Products for first responders or Doctors, or Students, etc.
Thank you Team! -
Cameron
MemberJuly 11, 2023 at 4:27 pm in reply to: DOWN PAYMENT ASSISTANCE FIRST-TIME HOMEBUYER WITH THE LENDER CAMERON LeCLAIRHello Gus,
Of course! “theNADA ” ( Meaning “Nothing” down ) This is an amazing program with amazing opportunity that allows 100% Financing for a Purchase for a first time homebuyer or actually ANY Primary Purchase that follows the HUD guidelines.
Nothing down with 100% FHA purchase financing.
One submission. One approval. One closing.
680 FICO Min
DTI per AUS ( Must Be Approved/Eligible )
Loan Amounts per county limits
First Time Homebuyer OK
Homeowner Education (at least one borrower) required
Follow FHA guidelines and DU findings
Non Occupying Co-Borrowers Allowed
DACA Borrowers eligibleIs the down payment assistance program forgivable or NOT forgivable.- No this product comes with a 10 Yr Fully Amortized 2nd lien for that 3.5% down which provides that 96.5/100% CLTV.
What is the minimum credit score requirements and debt-to-income ratio cap- Per AUS CAP 46/56.99% DTI- Must be Approved/Eligible & 680 Min FICO ( Only overlay with HUD, used to be Min 580 + ) i will update when we bring that back!
What is the mortgage rates and can you buy down the rate- Rates range from 6.25%- 7.625% ( today 7.25% is PAR ) with 7.625% paying back 1.665% in lender credit which could help the borrower with closing costs.
What is the credit and income requirements? Are there income caps? Is there household income cap? No Income, or AGI Caps, Per AUS!
What are overlays on top of agency guidelines? 680 Min FICO is our Only overlay with HUD, besides max units 2.
What type of down payment assistance program is it? Conventional loans, FHA loan, or VA loan? this Product is 100% FHA ONLY. We currently do not provide any other DPA product besides the CALHFA Grant program.
Can the Lender’s DPA program be lender paid or borrower paid or is there an option? We offer both for you & your client- typically with the way the market is right now, borrower paid is the best way to go for MAX credit & help with closing costs at cap rate, but we can get you that 2.75% no matter the case.
Remember- We allow 6% Seller Concessions- so if you got seller contributions USE THEM!
What is the minimum loan amount? $50k, but reach for the sky ! Nobody get paid on those. Plus 3% High cost will bite you at one point.
Are there states like Washington state where the down payment assistance program is not allowed? Yes, Washington, Kentucky, & Massachussetts, No Go on this product.
What are the parameters to qualify for the down payment assistance program? Do you need to be a first-time homebuyer? You do not need to be a first time homebuyer, but it needs to be a Primary purchase Only.
Can you have non-occupant co-borrowers? Yes
Can you be in an active Chapter 13 Bankruptcy repayment plan to qualify for the down payment assistance program? All BK’s need to be discharged- Ch.13 min 1 year with payments agreed on time. Ch.7 & 11 2 Years Discharged.
Can the down payment assistance program allow outstanding collections and charge off accounts or other derogatory credit tradelines? Collections cannot exceed $2k combined. Medical – OK Charge Offs- OK
What type of properties can you purchase with the down payment assistance program. 1-2 units • SFR, CONDO (HUD APPROVED), PUD, or Manufactured Homes
Do you need to complete a HUD approve housing class or any other courses to be eligible for the down payment assistance program? If client is FTHB, They must complete the First time Homebuyer education course- it will be conditioned.
Few other notes-
2nd lien for that 3.5% MUST be 2% higher than the 1st note rate- i.e if you have a 7.25% 1st , your 2nd rate will be 9.25%.
Regulated by HUD & no going around it, but Also, No PPP & that 3.5% 2nd is a tiny payment. Sell it!
NO PPP is the reason for the season. local grants or community seconds come with too many restrictions, this ones easy.
if you can do FHA- you can do this. Nothing else is different than adding the 3.5% Payment to DTI.Please let me know if you have any other questions!