 Dual-Licensed Mortgage and Real Estate Professionals
Jeannie
Dual-Licensed Mortgage and Real Estate ProfessionalsForum Replies Created
-

Buying a House in Kentucky: A Step-by-Step Guide
Determine Your Budget
- Evaluate Finances: Assess your income, expenses, and savings to determine how much you can afford for a down payment and monthly mortgage payments.
- Affordability Calculation: Use online calculators or consult a financial advisor to establish a comfortable mortgage payment range.
- Debt-to-income Ratio: Aim for a debt-to-income ratio below 43% to qualify for most mortgage loans.
Get Pre-Approved for a Mortgage
- Contact Lenders: Contact banks, credit unions, or mortgage brokers to get pre-approved.
- Documentation: Prepare necessary documents such as tax returns, pay stubs, bank statements, and credit reports.
- Pre-Approval Letter: Obtain a pre-approval letter to demonstrate your borrowing capacity and enhance your credibility with sellers.
Choose a Real Estate Agent
- Local Expertise: Select an agent with extensive knowledge of the Kentucky housing market.
- Agent Services: Your agent will help you find suitable properties, negotiate offers, and navigate the buying process.
- Referrals and Reviews: Seek referrals from friends and family or read online reviews to find a reputable agent.
Start House Hunting
- Search Tools: Utilize online real estate listings and your agent’s resources, and visit open houses to identify potential homes.
- Criteria List: Define your criteria, including location, size, budget, and essential features.
- Property Visits: Schedule visits to shortlisted properties to evaluate their condition and suitability.
Make an Offer
- Market Analysis: Work with your agent to perform a comparative market analysis to determine a fair offer price.
- Offer Letter: Submit a formal offer letter that includes your proposed price, contingencies, and closing timeline.
- Earnest Money: Be prepared to include an earnest money deposit as a sign of good faith.
Negotiate the Deal
- Counteroffers: Be ready for the seller to counter your offer. Discuss potential responses and strategies with your agent.
- Terms: Negotiate terms such as repairs, closing costs, and other contingencies.
- Final Agreement: Once both parties agree, sign the purchase agreement detailing the finalized terms.
Conduct Due Diligence
- Home Inspection: Hire a professional inspector to evaluate the home’s condition and identify potential issues.
- Appraisal: The lender will require an appraisal to confirm that the home’s value matches the loan amount.
- Title Search: Ensure a title search is conducted to check for any liens or legal issues with the property.
Secure Financing
- Final Mortgage Application: Complete the application process with your lender, providing all necessary documentation.
- Loan Approval: The lender will review your application, the property appraisal, and other factors before issuing final approval.
Close the Deal
- Review Documents: Carefully review all closing documents, including the loan agreement and settlement statement.
- Closing Costs: You should be prepared to pay closing costs, including lender fees, title insurance, and property taxes.
- Final Walkthrough: Conduct a final walkthrough of the property to ensure it is in the agreed-upon condition.
- Sign Documents: Attend the closing meeting to sign all necessary paperwork and officially take ownership of the home.
Post-Purchase Considerations
- Move-In: Plan your move, set up utilities, and change your address with relevant agencies.
- Home Maintenance: Schedule regular maintenance to preserve the home’s condition and value.
- Insurance: Ensure you have adequate homeowners insurance coverage to protect your investment.
Additional Tips
- Local Laws and Regulations: Familiarize yourself with Kentucky’s real estate laws and regulations, including property taxes and zoning laws.
- Homeowner Associations: If buying in a community with a homeowner association (HOA), review the HOA rules, fees, and any restrictions.
Climate Considerations: Be aware of Kentucky’s climate and weather patterns, including the potential for severe weather, and plan accordingly for home insurance and preparedness. By following these steps and working with knowledgeable professionals, you can navigate the process of buying a house in Kentucky smoothly and successfully.
-
Renovation VS Trade in RV. My friend Greg Stadlin of Collier RV in Northern Illinois referred me to one of his clients, David. David did a complete renovation of his 37 feet RV which included two new slide outs. I spoke with David today and he said he spent $150,000 to renovate his RV with two new slide outs, interior and exterior. He will send me pictures of before and after of his RV. I can stop by the storage at Collier RV and take a look. I have a 2001 Tiffin Zephyr 42 ft. coach with only 52,000 miles I was thinking of trading in for a newer one but am afraid of losing value. RVs depreciate more than any other property or vehicles.
-
I cannot stand to stomach a loss of one million or several hundred thousand dollars on a vehicle or RV. I suggest renovate the RV you have and forget about trading your existing RV for a brand new RV. It will drop 90% of the value in ten years anyways. RVs is like rent. Not an investment but rather an expense.
-
Bank statement mortgage loans are designed to help self-employed borrowers who may need traditional income documentation like W-2s or pay stubs. Here are the typical requirements for such loans:
Basic Requirements
Bank Statements:
- Duration: Usually, lenders require 12 to 24 months of personal or business bank statements.
- Account Information: Statements must include the account holder’s name, account number, statement date, beginning and ending balances, and details of deposits and withdrawals.
Income Calculation:
- Personal Bank Statements: Lenders typically add up the total deposits and average them over the statement period. Non-business-related deposits may be excluded.
- Business Bank Statements: Lenders often apply an expense ratio (typically 50%) to the total deposits to estimate the borrower’s net income.
Credit Score:
- A minimum credit score of 600 to 620 is generally required. However, some lenders have higher requirements depending on the loan amount and other factors.
Down Payment:
- Typically, a down payment of 10% to 20% is required. The exact amount may vary based on the lender’s policies and the borrower’s financial profile.
Reserves:
- Lenders might require borrowers to have reserves equivalent to several months of mortgage payments in savings or liquid assets.
Documentation:
- Proof of Business Ownership: A business license, incorporation articles, or an accountant’s letter.
- Profit and Loss Statement: Sometimes required to supplement bank statements.
- Identification: Valid government-issued ID.
Debt-to-Income Ratio (DTI):
- Lenders will calculate the DTI ratio using the income derived from bank statements. The maximum allowable DTI ratio is usually around 43-50%.
Property Requirements:
- The financed property must meet the lender’s type, location, and condition criteria.
Steps to Apply for a Bank Statement Mortgage Loan
Gather Documentation:
- Collect 12-24 months of consecutive bank statements.
- Ensure all statements are complete and show detailed transaction histories.
Contact Lenders:
- Reach out to lenders that offer bank statement loans. It’s beneficial to consult with mortgage brokers who can compare multiple lenders.
Submit Application:
- Fill out the loan application and submit all required documentation.
Income Calculation:
- Work with the lender to verify the calculated income based on bank statement deposits.
Loan Approval Process:
- The lender will review your application, credit history, and financial documents. They may ask for additional information during underwriting.
Loan Closing:
- Once approved, proceed with the closing process, including signing the loan agreement and paying any required closing costs.
Bank statement mortgage loans are tailored for self-employed individuals who find it challenging to qualify for traditional loans due to a lack of conventional income documentation. By providing bank statements that show a steady flow of deposits, borrowers can demonstrate their ability to repay the loan.
-
Thank you for providing information about obtaining an NMLS license in New York. Let’s break down the process:
- Apply the Nationwide Mortgage Licensing System (NMLS).
- This is the first step in the process.
- The NMLS is a centralized system for mortgage licensing.
Complete Pre-licensing Education Courses
- Twenty hours of NMLS-approved courses are required.
- This includes 3 hours specifically on New York law.
- These courses prepare you for the role of a mortgage loan originator.
Pass the SAFE Mortgage Loan Originator Test
- This test consists of a National Component with Uniform State Content.
- It assesses your knowledge of mortgages. Lending practices and regulations
Additional information that might be helpful:
Background Check and Fingerprinting: Most states require this as part of the licensing process
Credit Check: Your credit history may be reviewed
Sponsorship: It would help if you typically were sponsored by an NMLS-registered financial institution.
State-Specific Requirements: New York may have additional requirements beyond these basics
Continuing Education: After obtaining your license, you must complete annual continuing education to maintain it.
Would you like more detailed information on any of these steps or the responsibilities of a licensed mortgage loan originator in New York?
-
Wiring a light switch can seem intimidating, but it’s a relatively straightforward task that homeowners can tackle with proper precautions and instructions. Here’s a step-by-step guide on how to wire a light switch safely: Materials Needed to Wire a Light Switch:
- Light switch (single-pole or 3-way depending on your need)
- Electrical tape
- Wire stripper/cutter
- Non-contact voltage tester
- Screwdrivers (flathead and Phillips head)
Step 1: Turn Off the Power Locate the circuit breaker controlling the switch you’re working on and turn it off. Double-check that the power is off using a non-contact voltage tester on the switch terminals and the light fixture itself.
Step 2: Remove the Old Switch Using a flathead screwdriver, unscrew the switch plate cover and the switch itself from the electrical box. Carefully pull out the switch, taking note of which wires are connected to which terminals.
Step 3: Disconnect the Wires Unscrew the terminal screws and detach the wires from the old switch. Straighten the wires and strip about 3/4 inch of insulation from the ends using a wire stripper.
Step 4: Connect the Wires to the New Switch Connect the wires to the new switch terminals, ensuring a tight connection. The green or bare copper wire is the ground wire and should be connected to the green ground screw on the switch. The hot wire (usually black) connects to one terminal, and the neutral wire (usually white) connects to the other terminal.
Step 5: Secure the Switch Carefully tuck the wires into the electrical box, ensuring they’re not pinched or exposed. Secure the new switch to the electrical box using the mounting screws.
Step 6: Restore Power and Test Turn the circuit breaker back on and test the new switch by turning it on and off, ensuring the light fixture is working correctly.
Step 7: Install the Switch Plate Cover Once everything is working properly, install the switch plate cover using the mounting screws.
Remember to exercise caution when working with electricity and follow all safety protocols. If you’re uncomfortable or unsure about any part of the process, it’s best to consult a licensed electrician.
-
Peter Schiff nails it that FED Chairman Jerome Powell lies about inflation.
https://www.youtube.com/live/Yp6uGtxii18?si=YapAhSCOjAteDfVm
-
Rhonda, here is the frequently asked question on what is a gift of equity home purchase:
A gift of equity is a financial transaction in which a property is sold to a family member or close associate at a price below its market value. The difference between the market value and the selling price is considered a “gift” to the buyer. This concept is often used to help family members, particularly children, purchase a home with more favorable terms. Here’s how it works and some key points to consider:
How a Gift of Equity Works
- Property Appraisal: The property’s market value is determined through a formal appraisal.
- Sale Price: The seller agrees to sell the property to the buyer at a price lower than the appraised market value.
- Gift of Equity Amount: The difference between the appraised market value and the sale price is the gift of equity. For example, if a home is appraised at $300,000 and sold for $250,000, the gift of equity is $50,000.
- Down Payment: The gift of equity can be used by the buyer as a down payment on the property, potentially reducing or eliminating the need for additional down payment funds.
Benefits of a Gift of Equity
- Lower Down Payment: Buyers can use the gift of equity as part or all of their down payment, making it easier to afford the home purchase.
- Reduced Loan Amount: Since the sale price is lower than the market value, the buyer may need to take out a smaller loan.
- Favorable Loan Terms: The buyer may qualify for better loan terms due to the reduced loan amount and higher equity stake.
Tax Implications
- Gift Tax: The IRS treats a gift of equity as a taxable gift. However, the annual gift tax exclusion ($17,000 per recipient as of 2024) and the lifetime gift tax exemption ($12.92 million as of 2024) can apply, allowing many gifts of equity to avoid triggering gift taxes.
- Documentation: Proper documentation is essential. A gift letter from the seller to the buyer is typically required by lenders, stating that the gift is not a loan and does not need to be repaid.
Mortgage Considerations
- Lender Approval: Lenders often require specific documentation to approve a mortgage involving a gift of equity. This includes the appraisal, the sale contract, and the gift letter.
- Loan Programs: Some mortgage programs have specific guidelines for gifts of equity, so it’s important to consult with the lender to ensure compliance.
Steps to Execute a Gift of Equity Home Purchase
- Appraise the Property: Obtain a professional appraisal to determine the market value of the property.
- Agree on the Sale Price: Seller and buyer agree on a sale price that is below the market value, establishing the gift of equity amount.
- Prepare the Gift Letter: The seller provides a gift letter stating the amount of the gift of equity and confirming that it is a gift, not a loan.
- Loan Application: The buyer applies for a mortgage, using the gift of equity as part of the down payment.
- Close the Sale: Finalize the transaction with proper documentation and complete the home purchase process.
A gift of equity can be a valuable tool for facilitating the purchase of a home within a family, making homeownership more accessible. However, it’s important to understand the tax implications and mortgage requirements to ensure a smooth transaction. I do not know if the seller and buyer can qualify for a gift of equity home purchase. I suggest, you contact several wholesale rep especially @Christian Sorensen

gustancho.com
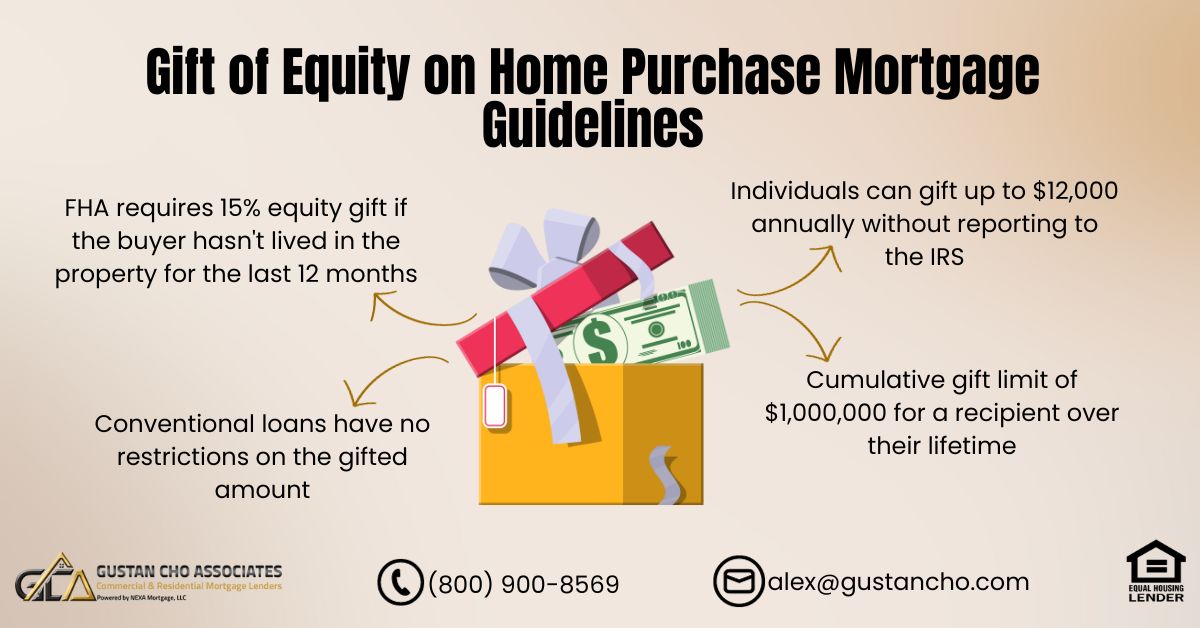
Gift Of Equity on Home Purchase Mortgage Guidelines
Gift of Equity on Home Purchase is when buying a home from a relative at below the appraised value and the seller is gifting you the equity.