 Dual-Licensed Mortgage and Real Estate Professionals
Lori
Dual-Licensed Mortgage and Real Estate ProfessionalsForum Replies Created
-
What is Airbnb and How Does It Work?
Airbnb is an online marketplace connecting people who want to rent their homes with those looking for accommodations. It offers unique and diverse lodging options, from single rooms to entire homes, and even unique spaces like treehouses and boats. Here’s a detailed overview of how Airbnb works:
How Airbnb WorksFor Guests
Search for a Listing:
Platform: Guests can use the Airbnb website or mobile app to search for listings based on location, date, price, property type, and amenities.
Filters: Filters can be applied to refine the search, such as entire home/apt, private room, shared room, or unique stays.
Review Listings:
- Details: Each listing includes detailed information about the property, including photos, descriptions, amenities, house rules, and reviews from previous guests.
- Host Profile: Information about the host, including a profile picture, verification status, and guest reviews, is also available.
Book a Stay:
- Instant Book: Some listings offer Instant Book, allowing guests to book immediately without host approval.
- Request to Book: Other listings require the guest to send a booking request, which the host can accept or decline.
- Payment: Payment is handled through Airbnb’s secure platform, which typically includes the nightly rate, cleaning fee, service fee, and applicable taxes.
Communication:
- Messaging: Airbnb provides a messaging system for guests and hosts to communicate before and during their stay.
- Support: Airbnb offers 24/7 customer support to assist with any issues.
Check-In and Stay:
- Instructions: Guests receive check-in instructions from the host, which may include a key exchange or self-check-in details.
- Stay: Guests stay at the property and are expected to follow house rules and respect the property.
Review:
- Review System: After the stay, guests and hosts can leave reviews, which helps build trust and inform future guests and hosts.
For Hosts
List Your Space:
- Create a Listing: Hosts can list their property on Airbnb by providing details about the space, amenities, and house rules and uploading photos.
- Pricing: Hosts set their prices, which can be adjusted for different seasons or demand periods. Airbnb provides pricing suggestions based on local market data.
Availability:
- Calendar: Hosts manage their calendar to indicate when the property is available for booking.
- Booking Settings: Hosts can choose booking preferences, such as minimum and maximum stay lengths and advance notice requirements.
Guest Interaction:
- Communication: Hosts communicate with potential guests through Airbnb’s messaging system to answer questions and provide additional information.
- Approval: Hosts review booking requests and decide whether to accept or decline them.
Prepare for Guests:
- Clean and Stock: Ensure the property is clean and stocked with essentials before guests arrive.
- Check-In Process: Provide guests with detailed check-in instructions.
Host the Stay:
- Support: Be available to assist guests with any issues during their stay.
- Follow-Up: Ensure guests have a positive experience by addressing any concerns promptly.
Get Paid:
- Payouts: Airbnb handles the payment process and typically releases funds to the host 24 hours after the guest checks in.
Benefits of Airbnb
For Guests:
- Variety: A wide range of lodging options are often cheaper than hotels.
- Unique Stays: Access to unique properties and experiences.
Flexibility: Flexible booking options and amenities.
For Hosts:
- Income: Opportunity to earn extra income from unused space.
- Control: Flexibility to set availability, pricing, and house rules.
- Support: Access to Airbnb’s customer support and host resources.
Airbnb provides a platform for travelers to find unique accommodations worldwide and for hosts to monetize their properties. Its comprehensive booking, communication, and payment system makes it a convenient and secure option for guests and hosts.
For more detailed information, you can visit the Airbnb website.

airbnb.com
Airbnb | Vacation rentals, cabins, beach houses, & more
Get an Airbnb for every kind of trip → 7 million vacation rentals → 2 million Guest Favorites → 220+ countries and regions worldwide
-

Training a brand new NMLS-licensed mortgage loan originator (MLO) to become a successful top-producing loan officer involves a combination of foundational education, practical experience, mentorship, and ongoing professional development. Here’s a detailed plan to achieve this goal:
Foundational Education and Training
Comprehensive Onboarding Program: Start with a structured training program like the NEXA Mortgage Academy, which offers in-depth knowledge on mortgage origination, industry best practices, compliance, and sales techniques. Utilize resources from the Mortgage Bankers Association (MBA) for foundational courses on mortgage lending.
Product Knowledge and Industry Regulations
Mortgage Products:
- Train on various mortgage products, including FHA, VA, USDA, conventional, jumbo loans, and specialty products.
- Understand the guidelines and requirements for each type of loan.
- Compliance and Regulations:
- Teach federal and state regulations, including RESPA, TILA, and ECOA, and the importance of compliance to avoid legal issues.
- Continuous education on changes in regulations and market conditions.
Practical Skills Development
Loan Origination Software: Hands-on training with Loan Origination Systems (LOS) such as Encompass, Calyx, or LendingPad.
Documentation and Process Management:
- Detailed training on handling loan applications, gathering required documentation, and understanding the underwriting process.
Sales and Marketing Training
Sales Techniques: Role-playing scenarios to develop effective sales skills, including borrower interviews, explaining loan products, and managing client expectations.
Lead Generation and Marketing: Strategies for generating leads through digital marketing, networking, referrals, and leveraging CRM systems like Salesforce or HubSpot.
Mentorship and Shadowing
Assign a Mentor: Pair the new MLO with an experienced mentor who can provide guidance, answer questions, and share best practices.
Shadowing: Allow the new MLO to shadow experienced loan officers to observe how they handle clients, process loans, and solve problems.
Performance Tracking and Feedback
Set Clear Goals: Establish achievable performance goals and metrics for the new MLO.
Regular Feedback: Provide consistent feedback on their progress, highlighting strengths and areas for improvement.
Building a Personal Brand and Network
Personal Branding: Teach how to build a brand through social media, professional networking, and community involvement.
Networking: Encourage participation in industry events, local business groups, and real estate associations to build a network of potential referral partners.
Ongoing Professional Development
Continuing Education: Encourage attending industry conferences, webinars, and workshops to stay updated on industry trends.
Advanced Training: Offer opportunities for advanced training in specialized areas such as reverse mortgages, commercial lending, or real estate investment financing.
Example Training Schedule
Week 1-2: Introduction to the mortgage industry, basic terminology, compliance training, and loan product understanding.
Week 3-4: In-depth training on loan origination software, documentation processes, and practical exercises.
Week 5-6:
- Sales training
- Role-playing client interactions
- Shadowing experienced loan officers
- Initial lead generation techniques
Week 7-8:
- Practical application of learned skills
- Managing real loan files under supervision
- Receiving regular feedback
Ongoing: Monthly compliance updates, quarterly sales training, continuous professional development, and networking activities.
-
Experiencing a last-minute mortgage denial can be frustrating and stressful, especially when it happens unexpectedly. Many borrowers face this situation due to inadequate loan officers or lender overlay qualifications. Here’s a breakdown of what you can do and why this happens:
Why Last-Minute Mortgage Denials Happen
Inadequate Qualification by Loan Officers: Sometimes, loan officers might need to thoroughly assess a borrower’s financial situation or overlook important details during the pre-approval process, leading to a denial later in the underwriting process.
Lender Overlays: These are additional guidelines imposed by lenders above the minimum requirements set by federal agencies like FHA, VA, USDA, Fannie Mae, or Freddie Mac. These overlays can vary significantly between lenders, causing issues for borrowers who might meet federal requirements but not the stricter lender-specific criteria.
Solutions and AlternativesGustan Cho Associates’ Approach
Gustan Cho Associates specializes in helping borrowers whom other lenders have denied. They operate on a no-lender overlay business model, meaning they adhere strictly to federal minimum guidelines without additional restrictive overlays. This flexibility allows them to assist a wider range of borrowers, including those with lower credit scores and unique financial situations.
Loan Options Available
Low Credit Score Loans: They can work with borrowers with credit scores as low as 500 FICO.
- Non-QM Loans: For those who do not qualify for traditional mortgages.
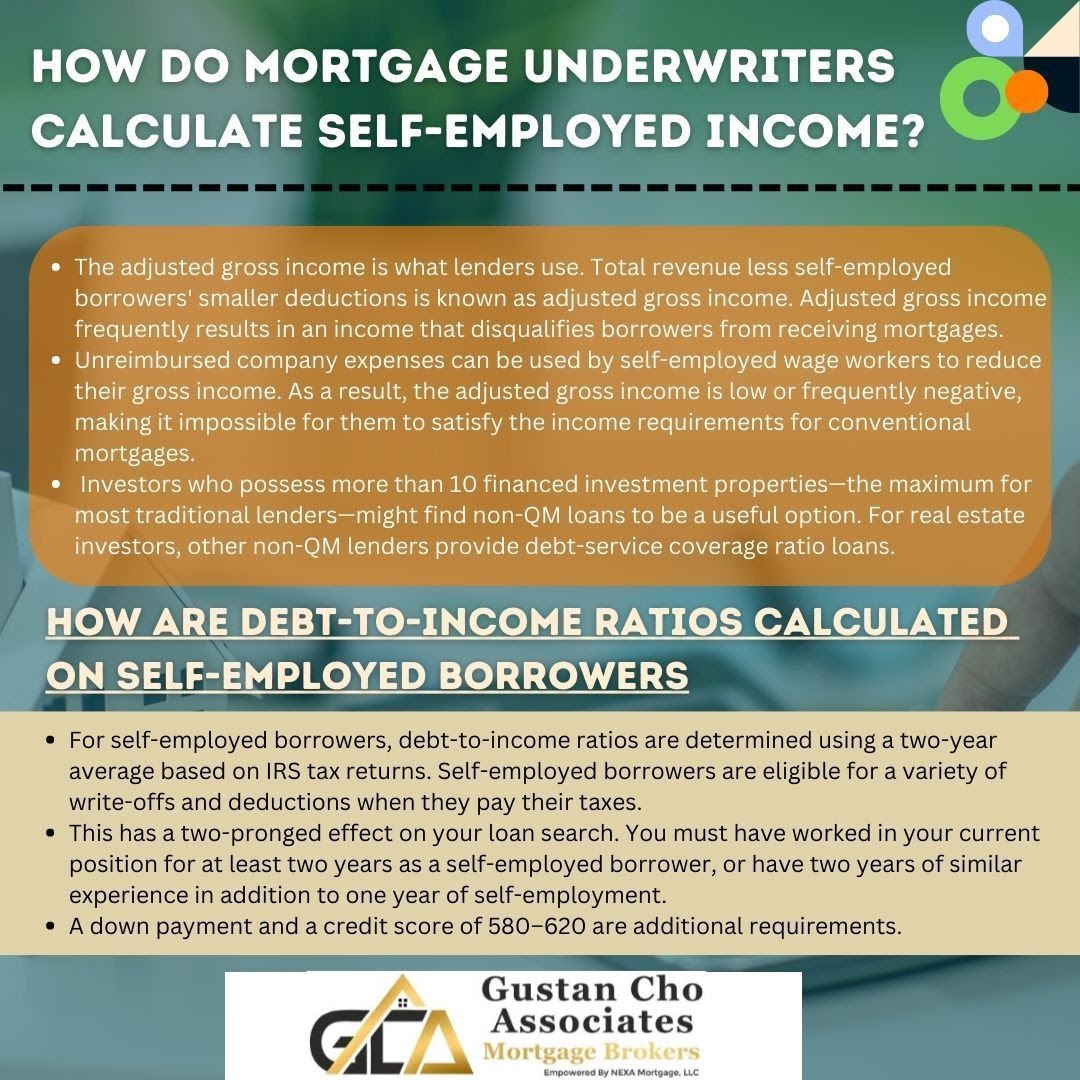
- 12-Month Bank Statement Loans: Ideal for self-employed individuals.
- DSCR Loans: For investment properties based on the property’s income potential rather than the borrower’s income.
- No-Doc Loans: For borrowers who cannot provide traditional income documentation.
- Specialty Loans: Including ITIN loans, DACA loans, and Condotel financing.
- Commercial Loans include SBA loans, hard money commercial loans, and equipment financing.
Steps to Take if You’ve Been Denied
Identify the Reason for Denial: It is crucial to understand why your mortgage application was denied. Request a detailed explanation from the lender.
Consider Alternative Lenders: Explore lenders like Gustan Cho Associates, which do not impose additional overlays and can accommodate unique financial situations.
Review and Improve Your Financial Profile: Take steps to improve your credit score, reduce debt, or increase your down payment.
Seek Professional Advice: Consult with a mortgage broker or financial advisor to understand your options and receive guidance tailored to your situation.
Contact Information and Next Steps
Gustan Cho Associates: Contact them for a consultation to discuss your specific needs and how they can assist you in getting approved for a mortgage or commercial loan. For more detailed information and assistance, you can visit their website at Gustan Cho Associates or contact their support team directly. By understanding the reasons for last-minute mortgage denials and exploring flexible lending options, you can find a path to approval and secure the financing you need.
gustancho.com
GCA Mortgage | Mortgage Experts With No Overlays
Whether you’ve gone through bankruptcy, divorce or you are a first-time homebuyer, Gustan Cho Associates are experts in difficult loans
-
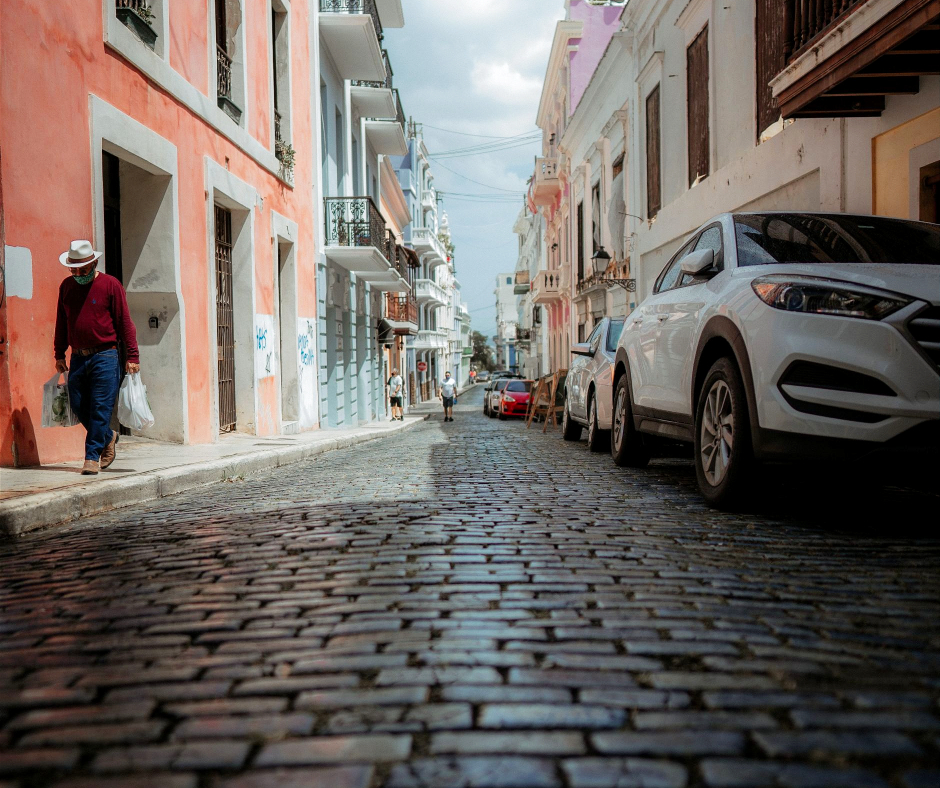
Steps to Buy Residential and Investment Real Estate in Puerto Rico
Buying real estate in Puerto Rico, whether for residential or investment purposes, involves several steps that ensure a smooth transaction and secure investment. Here’s a detailed guide to help you navigate the process:
Step 1: Research and Planning
Determine Your Purpose: Residential: If you plan to live in the property, consider factors like proximity to amenities, schools, and work.
Investment: If you’re buying for investment, focus on potential rental income, property appreciation, and market demand.
Set Your Budget: Assess your financial situation, including savings, income, and current debts. Determine how much you can afford for the down payment, monthly mortgage, and other related costs.
Market Research: Study the Puerto Rican real estate market. Look into property prices, market trends, and popular locations for both residential and investment properties.
Visit Puerto Rico:
- Visit Puerto Rico to explore different neighborhoods.
- Understand the local culture.
- Identify areas that meet your criteria.
Step 2: Get Pre-Approved for a Mortgage
Choose a Lender: Research and compare mortgage lenders, including local banks, credit unions, and international lenders familiar with Puerto Rican real estate transactions.
Submit an Application: To get pre-approved for a mortgage, provide the necessary financial information, including income, assets, debts, and credit history.
Receive Pre-Approval: Getting pre-approved gives you a clear idea of your budget and strengthens your position when making offers.
Step 3: Hire Professionals
Real Estate Agent: Find a licensed real estate agent in Puerto Rico who is experienced in the local market and can guide you through the buying process.
Attorney: Hire a local attorney specializing in real estate transactions to ensure all legal aspects are handled correctly.
Step 4: Property Search
Online Listings: Use real estate platforms to search for properties that meet your criteria.
Property Visits: Schedule visits to view properties in person. Take notes and pictures to compare options later.
Evaluate Potential Investments: Assess potential rental income, occupancy rates, and maintenance costs for investment properties.
Step 5: Make an Offer
Prepare the Offer: Work with your real estate agent to prepare a competitive offer based on the property’s market value and condition.
Negotiations: Be prepared to negotiate with the seller. Your agent can help you navigate this process and secure favorable terms.
Step 6: Conduct Due Diligence
Home Inspection: Hire a professional inspector to evaluate the property’s condition and identify potential issues.
Title Search: Your attorney will conduct a title search to ensure the property is free of liens and legal issues.
Appraisal: The lender will order an appraisal to determine the property’s market value.
Step 7: Review and Sign the Purchase Agreement
Agreement Review: Carefully review the purchase agreement with your attorney to ensure all terms are clear and acceptable.
Sign the Agreement: Sign the purchase agreement and provide the required earnest money deposit.
Step 8: Financing and Final Approval
Submit Final Documents: Provide any additional information requested by the lender to finalize your mortgage application.
Underwriting Review: The lender’s team will review all information to approve the loan.
Step 9: Closing Process
Final Walkthrough: Conduct a final walkthrough of the property to ensure it is in the agreed-upon condition.
Closing Documents: Review and sign all closing documents, including the deed and mortgage agreement.
Pay Closing Costs: You must pay any closing costs, including legal fees, title insurance, property taxes, and other associated costs.
Transfer of Ownership: You receive the keys to your new property, and the ownership of the property is transferred to you.
Additional Considerations:
Property Insurance: Ensure adequate property insurance, including coverage for natural disasters such as hurricanes and earthquakes.
Tax Benefits: Explore potential tax benefits and incentives for property owners in Puerto Rico, including Act 20 and Act 22, which offer tax incentives for certain types of investments and residents.
Cultural and Language: While many people in Puerto Rico speak English, Spanish is the primary language. Familiarize yourself with the local culture and language to make the transition smoother.
Utilities and Services: Set up electricity, water, and internet services: research local providers and their service options. Buying real estate in Puerto Rico, whether for residential or investment purposes, involves careful planning, thorough research, and working with experienced professionals. By following these steps and considering additional factors, you can navigate the process smoothly and successfully invest in Puerto Rican real estate.
https://gcaforums.com/buying-a-house-in-puerto-rico/
gcaforums.com
Things You Should Know Before Buying a House in Puerto Rico
People interested in buying a house in Puerto Rico need to be aware of several factors before shopping for homes. Getting a lender is the first step.
-
Mortgage Options for First-Time Homebuyers in Wisconsin
First-time homebuyers in Wisconsin have several mortgage options, each with unique benefits, requirements, and considerations. Here’s an overview of some of the best mortgage options for first-time homebuyers in Wisconsin:
Conventional Loans:
- Overview: These are traditional loans that the government does not insure. They typically require higher credit scores and down payments compared to government-backed loans.
- Down Payment: Usually between 3% to 20% of the home’s purchase price.
- Pros: Lower interest rates and no mortgage insurance requirement if you put down 20% or more.
- Cons: Stricter credit and income requirements.
FHA Loans:
- Overview: Backed by the Federal Housing Administration (FHA), these loans are designed to help first-time homebuyers and those with lower credit scores.
- Down Payment: As low as 3.5%.
- Pros: Lower credit score requirements (typically as low as 580) and smaller down payments.
- Cons: Requires mortgage insurance premiums (MIP), both upfront and annually.
VA Loans:
- Overview: Available to veterans, active-duty service members, and eligible surviving spouses. These loans are backed by the U.S. Department of Veterans Affairs (VA).
- Down Payment: No down payment is required.
- Pros: No mortgage insurance, competitive interest rates, and flexible credit requirements.
- Cons: Only available to eligible military members and certain qualifying individuals.
USDA Loans:
- Overview: Designed for rural homebuyers, these loans are backed by the U.S. Department of Agriculture (USDA).
- Down Payment: No down payment is required.
- Pros: Low interest rates and no down payment.
- Cons: Geographic and income restrictions apply; they are only available in designated rural areas.
WHEDA Loans:
- Overview: The Wisconsin Housing and Economic Development Authority (WHEDA) offers various mortgage programs to assist first-time homebuyers.
- Down Payment: As low as 3% with down payment assistance programs available.
- Pros: Competitive interest rates, down payment assistance, and reduced mortgage insurance.
- Cons: Income and purchase price limits apply, and you must complete a homebuyer education course.
Conventional 97 Loan:
- Overview: A conventional loan option that allows for a 3% down payment, backed by Fannie Mae and Freddie Mac.
- Down Payment: 3%.
- Pros: Low down payment, lower mortgage insurance costs than FHA loans, and potential for reduced private mortgage insurance (PMI) after reaching 20% equity.
- Cons: It requires good credit (typically 620 or higher), and income limits may apply.
Tips for First-Time Homebuyers in Wisconsin:
Check Your Credit Score: Your credit score determines your mortgage eligibility and interest rates. If necessary, aim to improve your score before applying for a loan.
Save for a Down Payment: Although some programs require little to no down payment, having a larger down payment can lower your monthly payments and increase your loan options.
Get Pre-Approved: Before house hunting, get pre-approved for a mortgage. This will give you a clear idea of your budget and make you a more attractive buyer to sellers.
Research First-Time Homebuyer Programs: Look into state and local programs to assist first-time homebuyers. WHEDA, for example, offers programs that can help with down payments and closing costs.
Compare Lenders: Compare mortgage rates and terms from different lenders. This can help you find the best deal and save money over the life of your loan.
Consider Total Costs: When budgeting, consider all costs associated with buying a home, including closing costs, property taxes, homeowners insurance, and maintenance expenses. First-time homebuyers in Wisconsin can access various mortgage options tailored to different financial situations and needs. By understanding the benefits and requirements of each type of loan and taking steps to improve your financial profile, you can find the mortgage that best fits your needs and make your dream of homeownership a reality.
Suppose you need personalized advice or more detailed information on these options. In that case, it’s always best to consult a mortgage professional or financial advisor.
https://gustancho.com/mortgage-with-unpaid-collections-in-wisconsin/
gustancho.com
Mortgage With Unpaid Collections in Wisconsin in 2022
Homebuyers can qualify for a mortgage with unpaid collections in Wisconsin. Borrowers do not have to pay off outstanding collections/charge offs
-
Tricia James: More Than a Mortgage Professional
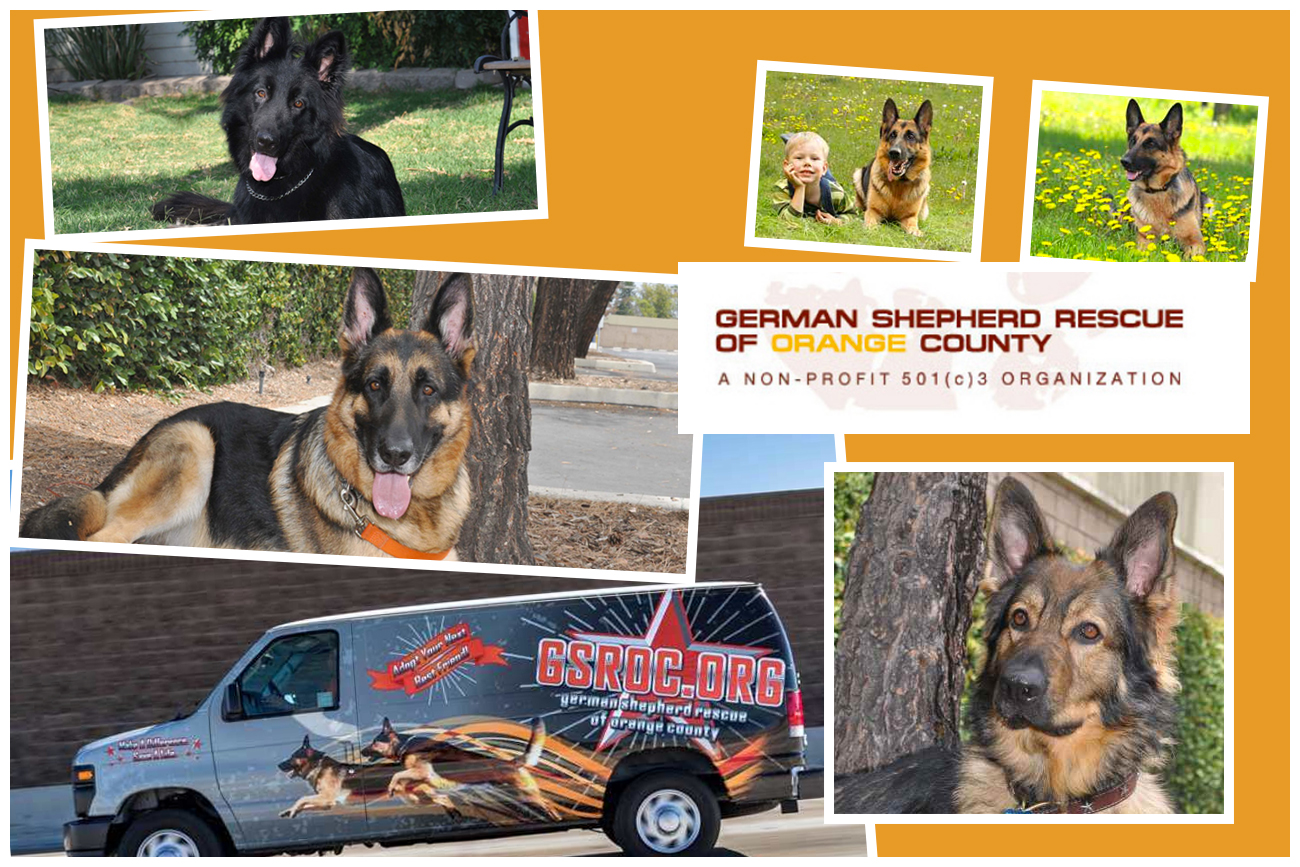
In addition to her impressive career as a Wholesale Account Representative at Champion Mortgage, Tricia James is dedicated to rescuing German Shepherd dogs. Her commitment to helping these animals showcases her compassionate nature and dedication to making a difference in the lives of her clients and animals in need.
Passion for Animal Rescue:
Rescue Efforts:
German Shepherd Dogs: Tricia focuses on rescuing and providing German shepherd dogs with a safe and loving environment. Her efforts help these animals find new homes and avoid abandonment or neglect.
Support and Rehabilitation: Beyond rescuing, Tricia rehabilitates these dogs, ensuring they receive the necessary medical care, training, and support to thrive in their new homes.
Community Involvement:
Networking with Shelters: Tricia works closely with local shelters and rescue organizations to identify needy German Shepherds and facilitate their rescue and adoption.
Advocacy and Awareness: Tricia raises awareness about the importance of animal welfare and responsible pet ownership by advocating for the rescue and adoption of German Shepherds.
Balancing Careers and Passion:
Tricia James exemplifies balancing a demanding professional career with a passionate commitment to community service. Her work in the mortgage industry and her dedication to animal rescue highlight her multifaceted personality and unwavering dedication to helping others. I can provide a list of reputable German Shepherd rescue centers in California. These are well-known organizations that often work with dedicated volunteers like Tricia:
German Shepherd Rescue Centers in California:
- German Shepherd Rescue of Orange County (GSROC):
- Location: Orange County, CA
- Description: GSROC is a non-profit organization dedicated to rescuing German Shepherd dogs and placing them in loving homes.
- Website: gsroc.org
Westside German Shepherd Rescue of Los Angeles:
- Location: Los Angeles, CA
- Description: This organization focuses on rescuing and rehoming German Shepherds from high-kill shelters and other dangerous situations.
- Website: sheprescue.org
German Shepherd Rescue of Northern California (GSRNC):
- Location: Northern California
- Description: GSRNC rescues German Shepherds throughout Northern California and places them in foster or permanent homes.
- Website: gsrnc.org
German Shepherd Rescue of Sacramento Valley:
- Location: Sacramento, CA
- Description: This organization works to rescue and find homes for German Shepherds in the Sacramento Valley area.
- Website: gsrsv.org
Second Chance German Shepherd Rescue:
- Location: Northern California
- Description: This rescue focuses on giving German Shepherds a second chance at life by rescuing them from shelters and placing them in loving homes.
- Website: scgsr.org
Volunteering and Getting Involved:
If you’re interested in volunteering or learning more about these organizations, visit their websites to learn about volunteer opportunities, donation options, and upcoming events. Volunteers like Tricia James are crucial to the success of these rescue efforts, providing care, support, and advocacy for these wonderful dogs.
If you need further assistance or specific information about Tricia James’s involvement, consider contacting the organizations directly or connecting with Tricia through professional or social channels. Tricia James is a standout professional in the wholesale mortgage industry and a compassionate advocate for German Shepherd dogs. Her dual commitment to her career and animal rescue efforts underscores her dedication to positively impacting various aspects of her life. If you would like to learn more about Tricia’s work or get involved in German Shepherd rescue efforts, feel free to ask!
gsroc.org
GSROC is a non-profit 501c(3) organization dedicated to rescuing and rehabilitating. View our available dogs and adopt a German Shepherd today.
- German Shepherd Rescue of Orange County (GSROC):
-
The down payment on a home purchase is a fixed amount depending on the mortgage loan program. For example, FHA loans require a 3.5% down payment, primary owner-occupant conventional loans require 3% for a first-time homebuyer and 5% for a homebuyer who owned a home in the past three years. VA loans and USDA loans do not require down payment. Second homes require a 10% down payment on conventional loans. Investment home loans require 15% on conventional loans. This is only on single family homes. Multi-unit family owner-occupant homes require 3.5% down payment on FHA loans and 5% down payment on conventional loans. Most homebuyers can cover closing costs with a combination of seller concession and lender credit. Lender credit is when the lender gives you funds to use for closing costs in lieu of a higher rate.
-
Lori
MemberMay 12, 2024 at 4:38 pm in reply to: Do I Need a Permit to Build a ADU or Tiny Home on my Property in FloridaYou generally need a permit to build an accessory dwelling unit (ADU) or tiny home on your property in most counties. Normally building permits are under the jurisdiction of cities and counties. However, specific requirements vary depending on the city or county you live in. Here’s what to consider:
1. Check Local Zoning Regulations:
- Each municipality or county has its own zoning laws that govern the construction of ADUs or tiny homes.
- Some areas may have strict rules on the size, height, location, and usage of ADUs.
- Zoning codes often determine whether ADUs or tiny homes are allowed in certain neighborhoods.
2. Permitting Process:
- Building Permit: You will likely need a building permit, which involves submitting plans to the local building department for approval.
- Electrical, Plumbing, and Mechanical Permits: Separate permits may be needed if your ADU or tiny home requires new plumbing, electrical, or HVAC systems.
- Utility Connections: Check for any additional requirements for hooking up to existing water, sewage, and electrical systems.
3. Building Codes:
- ADUs and tiny homes must adhere to the local building codes, which ensure the structure is safe and habitable.
- This may include specifications for foundation, insulation, emergency exits, and fire safety.
4. Homeowner Associations (HOAs):
- If you live in a community with a homeowners association, check their rules before starting construction. HOAs can enforce additional restrictions.
5. Impact Fees:
- Some cities or counties impose impact fees to cover the additional infrastructure costs incurred by adding new housing units.
6. Legal and Tax Considerations:
- Adding an ADU or tiny home can affect your property taxes and insurance, so consult a professional to understand the implications.
7. Other Permits:
- If the ADU or tiny home is intended for rental purposes, you may need a business license or short-term rental permit.
To ensure compliance with local regulations and to avoid penalties, start by contacting your local building or planning department. They will provide guidelines specific to your area, and you can better understand the requirements and steps for obtaining the necessary permits
-
Lori
MemberMay 12, 2024 at 4:27 pm in reply to: Do I Need a Permit to Build a ADU or Tiny Home on my Property in Texasin my opinion, the question to do i need a building permit to build an ADU in Texas is the following from what I know:
In Texas, whether you need a building permit to construct an accessory dwelling unit (ADU) depends on the specific municipality where the ADU will be located, as regulation is handled at the local level.
However, in general, most cities and counties in Texas do require a building permit for new ADU construction. Some key points about ADU permits in Texas:
Building Codes: Even if no permit is required by the local jurisdiction, ADUs must still meet all applicable building codes and zoning regulations.
Permit Requirements Vary: Permit exemptions, if any, are up to each individual city or county. Many major cities like Austin, Houston, San Antonio and Dallas require permits for ADUs.
Size Thresholds: Some areas may exempt ADUs under a certain square footage from permits, but common thresholds are very small like <200 sq ft.
Inspections: Even if no permit is technically required, most cities will want to inspect ADU construction for safety. Permits facilitate those inspections.
HOAs: Homeowners associations may have their own ADU approval processes regardless of municipal permit rules.
So in summary, while there could potentially be some very small municipal exemptions, for most homeowners in Texas looking to build an ADU, getting the proper permits from their local governing body is highly recommended and likely required. Check with your city/county planning department to verify their specific ADU permitting process.