 Dual-Licensed Mortgage and Real Estate Professionals
Lori
Dual-Licensed Mortgage and Real Estate ProfessionalsForum Replies Created
-

Heres a video clip of Chase and Skylar playing tag today
Change Thumbnail -
Generating thumbnail…
-
Generating thumbnail…
-
-
Here’s my Long Hair Black and Red German Shepherd, Chase and Skylar. The Black German Shepherd needs a good homes Laurie and I will adopt him on Friday.
-
Hello,
Thank you for reaching out, and I apologize that our contact form was not working. We appreciate you posting your information here.
Yes, we would be happy to review your refinance and provide you with available options. Based on the information provided—a single-family home valued at approximately $740,000–$750,000 and fair credit—we would need a few additional details before giving you an accurate quote.
Please do not post personal or sensitive information publicly on the forum. We will need to review:
- Current mortgage balance and approximate interest rate
- Whether you are looking for a rate-and-term refinance or cash-out refinance
- Estimated credit score, if known
- Property state
- Whether this is your primary residence, second home, or investment property
- Approximate monthly income and employment type
- Desired loan amount or amount of cash you would like to receive, if applicable
A fair credit score does not automatically prevent you from refinancing. Depending on the complete scenario, we can review conventional, FHA, VA if eligible, and alternative/non-QM refinance programs.
Once we have the complete information, we can determine which programs may fit and provide a more meaningful rate and cost comparison rather than quoting a rate without knowing the full loan scenario.
Thank you again for contacting Gustan Cho Associates. We look forward to helping you explore your refinance options.
Gustan Cho Associates
A DBA of Coast 2 Coast Mortgage Lending, LLC
NMLS 376205Information provided is for educational purposes and is not a commitment to lend. Loan approval, interest rates, and terms are subject to borrower qualification, property eligibility, underwriting, and applicable program requirements. Equal Housing Opportunity.
-
How does USDA Calculate Income? Lets take a case scenario in two different counties. $350,000 purchase . Homebuyer is single with one person in household and makes $125,000 buying a single family home in Harpers Ferry West Virginia. Will this borrower qualify on income? Second case scenario. Household of 4 buying a $475,000 home in Jefferson County Ohio. Gross income $165,000. Would they qualify on income on a USDA LOAN be?
-
Lori
MemberAugust 13, 2026 at 3:00 pm in reply to: GCA Mortgage Forums News for Thursday August 13 2026Wall Street giants like Citadel Securities and Citi are signaling a massive precious metals breakout, with Citi forecasting silver could surge to $70. As skyrocketing sovereign debt collides with an unprecedented AI capital expenditure cycle, plummeting new discoveries, and central bank buying from China’s Central Huijin, physical gold and silver face an explosive squeeze. Discover how these macro catalysts and shifting gold-to-silver ratios create an incredible setup for gold, silver, and precious metal mining stock investors.
SILVER and GOLD
https://www.youtube.com/live/nZq8MA3SMvU?si=rKPFkoE_VRqyndg7
-
Financial challenges often arise when bills, housing costs, or debt become difficult to manage. If you live in Seattle and are considering a Home Equity Line of Credit (HELOC), 401(k), retirement account, or business asset, use caution before sharing personal information or signing any documents.
Conduct due diligence and research all financial offers. Confirm the company’s name, verify its licensing, and request a written offer outlining terms, fees, repayment schedules, and risks related to home equity or retirement savings. Do not share bank statements, account numbers, Social Security numbers, passwords, or initiate wire transfers through unsecured platforms or with unverified parties.
More homeowners are struggling to meet mortgage obligations. If you face this challenge, contact your mortgage servicer and consult a HUD-approved housing counselor before using retirement savings or business assets.
-
This post covers financial assistance, business ownership, HELOCs, and retirement accounts. Because of the sensitive nature of these topics, members should stay vigilant and carefully assess any opportunity before sharing personal or financial information. Anyone presenting an opportunity must provide detailed information, including the nature of the opportunity, company name, costs, risks, potential benefits, and required qualifications. Members should not share Social Security numbers, bank statements, HELOC or retirement account details, passwords, or send funds to WhatsApp or unverified parties.s.
Members having difficulty with mortgage payments should consult their loan servicer, a HUD-approved housing counselor, or a licensed financial counselor before using home equity, retirement savings, or business resources.
-
Understanding Mortgage Underwriting
Once your loan documents are gathered, the next step is underwriting, which determines if your loan gets approved. A computer reviews your application first, followed by a person who looks at your risk as a borrower. Knowing how this works can help you avoid issues and keep your closing on track.
This guide explains how automated and manual underwriting work, points out common problems, and offers tips to help make your next underwriting experience easier and less stressful.
Defining Mortgage Underwriting
Mortgage underwriting is the process by which the lender reviews your application to determine whether you qualify, and which loan is right for you.
The underwriter reviews all the details to ensure your file meets the risk standards for investors who may buy your loan. Underwriters work behind the scenes and are separate from loan officers and processors.
They rarely speak directly with borrowers. Instead, they depend entirely on your documents, such as income records, credit reports, asset statements, appraisals, and title reports.
Their Verdict Hinges on Three Key Factors:
- Capacity: Can the borrower afford to pay their current debts?
- Credit: Does the borrower have a good credit history? If your application meets all the requirements, you will likely be approved. If not, you may get a list of issues to fix or, in some cases, be denied.
Manual Underwriting vs. Automated Underwriting
Most loans go through an Automated Underwriting System (AUS), which often streamlines the process and makes manual underwriting unnecessary.
Fannie Mae and Freddie Mac have sped up underwriting with their systems, Desktop Underwriter (DU) and Loan Product Advisor (LPA).
Loan officers enter your financial details, such as income, assets, debts, and credit report, into the AUS, which gives a decision in just minutes.
The Results Usually Come Within Minutes and May Include:
- Approve/Eligible (or “Accept”)
- Refer/Eligible: requires manual underwriting.
- A result of “Refer with Caution” or “Ineligible” usually means rejection unless the loan can be reworked.
- The AUS looks closely at your credit score, debt-to-income (DTI) ratio, and loan-to-value (LTV) ratio.
- Manual underwriting is needed for FHA loans if the borrower’s credit score is below 580 with a 3.5% down payment, below 500 with a 10% down payment, or if the debt-to-income ratio is 43% or higher.
How Manual Underwriting Works
In manual underwriting, the automated review is skipped, and a person reviews your financial documents. This happens for about 20% of conventional loans, 35% of VA loans, 25% of USDA loans, and 40% of jumbo loans. It’s also needed for FHA borrowers with a credit score below 620 or a debt-to-income ratio above the automated system’s limit. Manual underwriting usually takes longer, about 10 to 21 days, while automated reviews take just a day or two.
It also requires more paperwork, like a year of bank statements, two years of tax returns, job verification, and letters explaining any credit issues.
Still, manual underwriting can help about 15-25% of people denied by automated systems are approved when they demonstrate strengths such as good savings, a strong rent history, or a low housing expense-to-income ratio. These positives can even allow your DTI to be 5-7 points higher than normal limits.
The 3 C’s the Underwriter Actually Looks At
If you have had a recent bankruptcy or credit problem, it helps to work with lenders who are well-versed in manual underwriting and non-QM programs. Many underwriters are less familiar with cases that do not fit automated systems.
Capacity (Income and Debt-to-Income Ratio)
Underwriters verify income using pay stubs, W-2s, tax returns, and employment verification. They calculate two debt-to-income (DTI) ratios during the assessment.
Front-End DTI: Housing Payment / Gross Monthly Income
- Back-End DTI: Total monthly debt payments (including housing) divided by gross monthly income
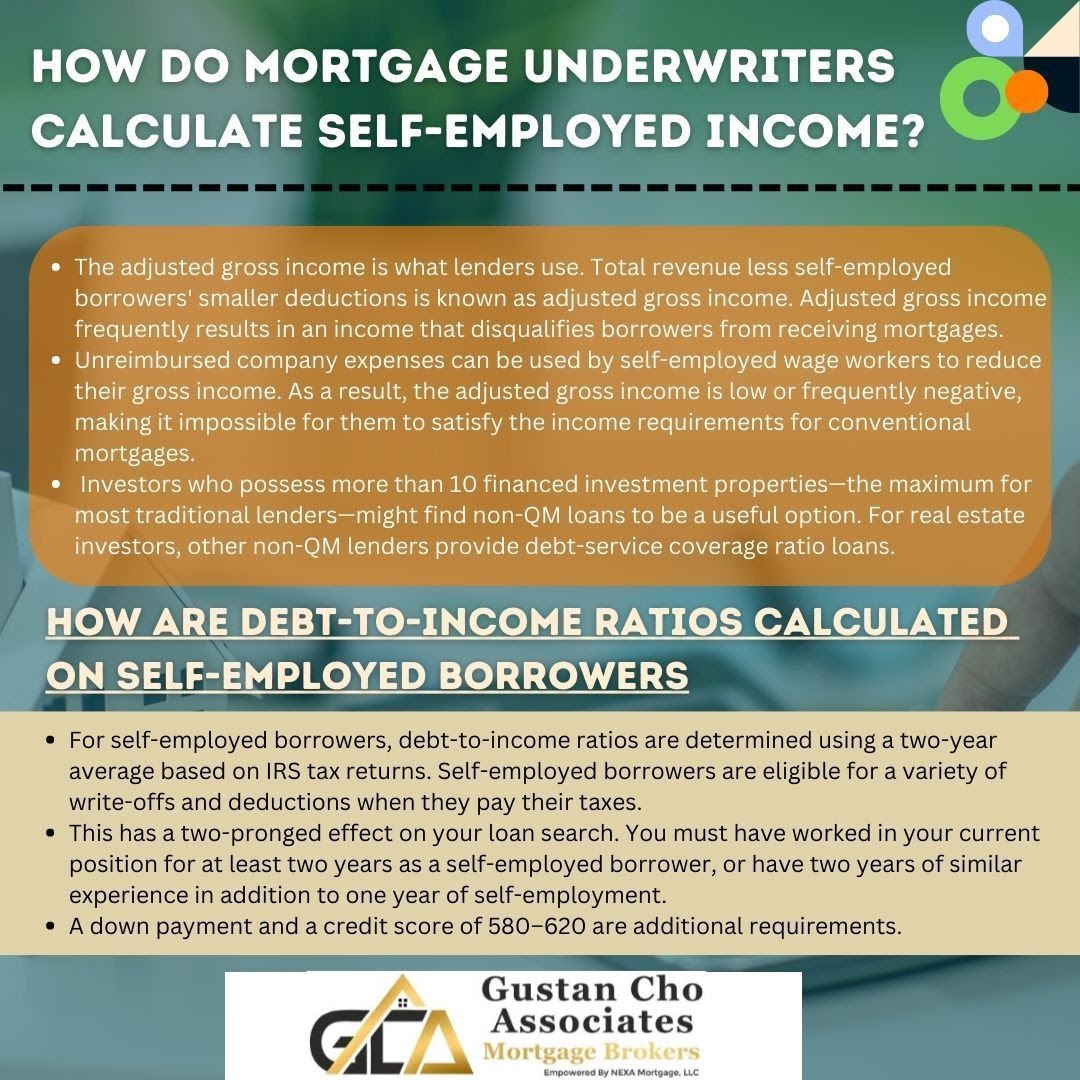
FHA rules usually limit the front-end debt-to-income ratio to 31% and the back end to 43%, but there are exceptions for people with strong reasons or those using manual underwriting. If you are self-employed, expect a closer review. Underwriters will check two years of tax returns, look at depreciation and other deductions, and focus on your business income over time, not just last year.
- Late payments, charge-offs, collections, and the overall payment history
- How credit accounts are being utilized
- Major derogatory events and the time that has passed since bankruptcy, foreclosure, short sale, discharge, or settlement
- Length of credit history and credit mix
Many borrowers think a Chapter 7 bankruptcy keeps them from getting a loan for years. In reality, FHA and VA rules, as well as many non-QM programs, set specific waiting times after bankruptcy. Non-QM options are often more flexible with timing and paperwork than regular loans.
Collateral
The underwriter checks that the home’s value supports the loan by reviewing the appraisal and title report for any claims, judgments, or problems. If the appraisal is lower than the purchase price, the loan can’t be approved as is. Then you might renegotiate, pay more, or cancel the deal.
Step-by-Step: What Happens During Underwriting
- File submission — The loan officer and processor submit the complete application package, which includes income documentation, asset statements, credit authorization, and the purchase contract or refinance request.
- Automated underwriting run — DU or LPA prepares a recommendation and a list of documentation needs.
- Underwriter review: A person reviews the automated system’s results and your documents, looking for anything, the computer might have missed, such as unexplained large deposits or discrepancies between your reported income and your pay stubs.
Conditional Approval: Most Loans are Not Approved Right Away.
- You’ll get a list of outstanding items to provide, such as updated bank statements, insurance letters, proof of insurance, or gift letters.
- Condition clearing — You and your loan officer send in the requested documents.
- This step can take longer because delays often happen when responses are slow or when paperwork is missing.
- Clear to close — When you’ve met every last condition, the underwriter gives the final thumbs-up and sends your file to closing.
- The numbers are set, and your closing date is on the calendar.
Common Reasons Underwriting Gets Delayed or Denied
- Large deposits that are unexplained or cannot be traced to a source with supporting evidence.
- Any gap or change in your employment during the loan process can raise concerns, especially if you transition from a regular salary to self-employment.
- Opening new credit accounts or making large purchases after pre-approval but before closing can also hurt your application.
- Income documents don’t match, like pay stubs that don’t agree with W-2s or tax returns that don’t match other statements.
- Low appraisal values or an appraiser noting a required repair.
- New debt amounts make the debt-to-income ratio go over the allowed limits.
Mortgage experts advise borrowers to avoid actions that could jeopardize approval, such assuch as changing jobs, opening new credit cards, making large purchases, or moving large sums of money without proof.
Underwriting Across Loan Types
In 2026, the maximum loan amounts for conforming loans rose to $832,750 for most one-unit homes and $1,249,125 in expensive areas. These limits determine whether a loan is conforming or jumbo, but don’t directly affect approval. The main underwriting factors are income, credit score, debt-to-income ratio, and down payment.
How to Get Through Underwriting Smoothly
- Collect all your documents before you apply. Having two years of tax returns, recent pay stubs, and bank statements ready can speed up the process a lot.
- Changes during underwriting may raise concerns for the lender.
- Avoid buying a new car, opening a credit card, changing jobs, or making any financial moves that might cause concern.
- To keep underwriting moving, send any requested documents as soon as you can.
- You’ll move through the process faster if you provide documents within a day or two instead of waiting weeks.
- Let your loan officer know right away about any bankruptcies, foreclosures, or late payments from the start.
- Applicants should look for lenders who offer manual underwriting and non-QM options.
- If you’re self-employed or have recent credit issues, you’ll often get better results with lenders who offer manual underwriting and non-QM programs instead of those who only use automated approvals.
- To move through the process smoothly, be organized, responsive, and honest.
If your situation is unique, such as being self-employed, recently filing bankruptcy, or buying an unusual property, look for lenders who offer manual underwriting.
Gustan Cho Associates is a licensed mortgage company operating in multiple states. The team specializes in manual underwriting and in FHA, VA, USDA, and Non-QM lending, benefiting clients with complex financial situations, including those with credit events such as bankruptcy or foreclosure.
For information on qualifying loan programs and to begin the pre-qualification process, contact Gustan Cho Associates.
Mortgage Loan Underwriting Process for Home Buyers
gustancho.com
Mortgage Loan Underwriting Process for Home Buyers
The Mortgage Loan Underwriting Process starts with the pre-approval stage then moves to processing, underwriting, closing, and funding.
-
If you use the money from selling your current home as a larger down payment on your next one, you can save a lot on future mortgage payments.
If you expect to have $60,000 to $70,000 after selling, Gustan Cho Associates can help you make the most of this money with these options:
– Make a larger down payment to lower the principal on your new loan
– Use the sale proceeds to pay for closing costs and prepaid expenses
– Set aside some of the sale proceeds to meet required cash reserves
– Use the sale proceeds to buy a less expensive home, which can lower your monthly paymentHow affordable your new home and mortgage will be depended on your income, credit, debts, job status, purchase price, and the proceeds from your sale. Getting pre-approved for a mortgage early can make planning your sale and next purchase much easier.
If you need to sell your current home before buying a new one, Gustan Cho Associates can apply for your mortgage with a home-sale contingency or look at other options based on your expected closing date. After the sale, the lender will record the money you made from the sale in the Home Purchase Transaction using a Closing Disclosure.
To keep your monthly payment affordable, you can choose a smaller loan, make a larger down payment, or buy a less expensive home. Your interest rate, property taxes, homeowners’ insurance, and mortgage insurance also affect your costs. Gustan Cho Associates will explain your total monthly payment and help you find a price that fits your budget before you make an offer.
Gustan Cho Associates will review your situation, from your expected sale proceeds to your ideal monthly payment and recommend the loan option that fits your next home purchase best.
Selling Your Home » Gustan Cho Associates
gustancho.com
Selling Your Home » Gustan Cho Associates
The housing market is booming. Sellers can get top dollar for their homes by following our tips and advice on selling your home from the guides below: