 Dual-Licensed Mortgage and Real Estate Professionals
Ollie
Dual-Licensed Mortgage and Real Estate ProfessionalsForum Replies Created
-

Ollie
MemberJuly 17, 2024 at 5:39 pm in reply to: What Are The Biggest Reasons People Are Moving Out of CaliforniaI would like to know these points further in detail and discuss the above topics further. Can you expand the above subject matters further?
-
To be approved for an unsecured $250,000 business credit card, one must prepare carefully, have a good financial history, and develop a solid business plan. Here’s how you can do it step by step:
Comprehend the Requirements
Before applying, you need to know the typical requirements for such a high credit limit. Usually, issuers want to see:
Good Credit History: Both personal credit scores (usually 720+) and business credit scores should be excellent.
Income Stability: Prove that your income is stable enough to repay this kind of credit, usually through steady business revenue.
Business Establishment: Lenders typically prefer businesses that have been in operation for at least two or three years;
Low Debt-to-Income Ratio: Show that your company has manageable debts relative to its income.
Boost Your Credit Scores
Personal Credit Score
Obtain Your Credit Reports: Get copies of your credit reports from major bureaus (Equifax, Experian, TransUnion) and check them for errors.
Pay Bills On Time: Make sure every bill gets paid when due, including current cards and loans;
Reduce Debts: Pay some outstanding debts to improve your credit utilization ratio.
Business Credit Score
Build Business Credit by Registering with business credit bureaus like Dun & Bradstreet Ex, Perian Business, Equifax Business, etc.
Open Business Credit Accounts: Ensure that you maintain a positive payment history with suppliers/vendors/lenders who report these accounts to commercial bureaus;
Monitor Your Business Credit: Review the information in your file at least once yearly and correct any mistakes immediately upon discovery.
Arrange Financial Documents
Lenders need detailed financial information about you to evaluate whether they should lend money or not:
Income Statements and Balance Sheets Reflecting Your Company’s Financial Health—Provide lenders with relevant past performance data on cash flows generated by operations over periods specified in advance during negotiations.
Tax Returns For The Past Two To Three Years — Both Personal And Business Taxes Should Be Filed Accurately So That No Penalties Are Incurred From Either IRS Or State Authorities Which Would Negatively Impact the Applicant’s Creditworthiness Rating. Bank statements from recent months show business revenue flowing in and out of accounts regularly.
Business Plan Covering Everything About Your Business Model.
How Much Money You Expect It To Make Over What Periods (With Supporting Documentation), And How This Credit Will Be Used To Achieve Those Projections.
Create a Relationship With the Lender
Knowing the lender well can improve your chances of being approved.
Open Accounts: Start with a business checking and savings account at the bank where you intend to apply for credit.
Use Business Services: You can apply for other types of loans or merchant services offered by this bank or any other trusted financial institution within its network.
Maintain Good Standing: Always keep all accounts active & current while maintaining steady growth through diversification into new markets/sectors domestically and internationally so as not to appear dormant;
Choose the Appropriate Card
Not all business cards give high limits; some research is necessary:
Compare Card Benefits: Look at rewards such as cash back on purchases made or travel insurance protection offered, etc.; also consider interest rates charged by different lenders offering these credit facilities;
Read Fine Print: Understand all fees associated with using this particular card, including the annual percentage rate charged on balances carried over from a month-to-month basis, i.e., minimum payments required each billing cycle until paid in full, etcetera.
Put Together A Strong Application File
When you are ready to apply, make sure that everything about your application looks good enough for approval:
Complete All Sections: Fill out every section truthfully so there will be a clear understanding later when they review it again, especially if asked questions relating directly or indirectly to the creditworthiness assessment process.
Supporting Documents: Attach all necessary financial statements and other relevant papers they may require during their evaluation, such as bank statements showing inflows/outflows, etcetera.
Cover Letter: Write a brief cover letter that should include information about the nature of your business, its financial health status, and why you need this particular amount of money now rather than later on another date.
Secured Business Loan As A Stepping Stone
If getting approved for an unsecured $250,000 business credit card proves next to impossible, what else can one do? Try these steps.
Secured Business Loan: Offer some valuable asset(s) owned outright by yourself or jointly held with others who have consented to it so that it can act as collateral/security for obtaining said loan, then show responsible borrowing behaviors over time, which will lead towards qualifying eventually being granted access into higher amounts without any security requirements attached anymore.
Gradually Increase Credit Limits: Request lower-limit cards initially while working hard towards growing and demonstrating reliability through timely monthly repayments before applying for bigger ones later when better placed financially.
Look for professional help if you need clarification on the process or need help.
Financial advisors: Review your finances and provide advice by contacting an accountant or financial adviser.
Credit consultants: Enhance your credit profile and navigate the application process with a business credit specialist. In summary, to secure a $250,000 unsecured business credit card, one needs a strong financial foundation, thorough preparation, and strategic thinking. You can increase your chances of being approved by improving your credit ratings, sorting out all required documents in advance, developing rapport with your lender, and making the right choice regarding cards. Seeking professional guidance can also make this whole thing faster and easier while helping you realize various objectives of financing your enterprise.
-
Equipment Financing and Leasing with No Money Down
Equipment financing and leasing with no money down is an eye-catching scheme for businesses wishing to procure vital equipment without making an upfront capital investment. This financial tactic lets companies keep the necessary tools and machinery for operation and expansion while saving their cash flow.
Understanding Equipment Financing and Leasing
Equipment Financing
Definition: Equipment financing refers to gaining a loan used specifically for purchasing equipment, which acts as collateral until it is paid off; thus, the lender retains a security interest over such items.
Ownership: The borrower becomes the owner of all the equipment from its inception but makes monthly installments to repay the debt.
Terms: Generally, loans last between two and seven years, depending on the kind of machines being financed and the different lenders’ policies.
Equipment Leasing
Definition: This concept is quite similar to renting because one gets into possession through making regular payments over some time frame without necessarily owning them at any point in time after that – it could be said that they are only borrowed temporarily;
Types of leases:
Operating Lease: This is a short-term lease in which the lessor remains the rightful owner throughout; the lessee can return or upgrade this item when the agreement period elapses.
Finance Lease (Capital Lease): This is a long-term rental agreement that functions more like borrowing money from a bank via loan facilities; here, enterprises have options whether or not to buy out the leased property at the end date, usually paying a small amount known as a “bargain purchase option.”
Flexibility: With technological advancements happening very frequently nowadays, a car might become outdated within just a few months after purchase, but if you lease, there will always be a chance for upgrading whenever needed, so flexibility becomes a key advantage under such circumstances, too.
Benefits of No Money Down Options
Preserving Cash Flow
Liquidity: Keeping reserves untouched thanks to the absence of an initial deposit required when going in for a contract may turn out to be an extremely important factor aimed towards meeting day-to-day needs as well as covering unexpected expenses that could arise from time to time;
Investment Opportunities: Businesses can channel saved funds into other areas, such as human resource development, marketing, or increasing stock levels.
Access to Equipment
Immediate Use: Immediate possession is guaranteed once terms are agreed upon; therefore, there is no need to wait until enough money has been set aside as a down payment before being allowed to take home needed assets;
Competitive Edge: If only one company within an industry uses the latest technologies while others continue using outdated ones, it automatically gains a competitive advantage over its rivals by working smarter, not harder. This improves efficiency levels, leading to higher productivity rates.
Tax Benefits
Deductions: Usually, lease payments and interest paid on loans taken qualify as deductible expenses, which implies that they might end up reducing taxable income considerably for most enterprises involved in such transactions;
Section 179 Deduction: This allows firms purchasing financed equipment to benefit from deducting the whole purchase price immediately instead of spreading it over several years, thereby giving them immediate relief on their tax obligations.
Potential Drawbacks
Higher Costs
Interest Rates: Normally, lenders charge higher interest rates whenever there is no upfront payment made since this move helps them offset risks associated with lending money without getting anything tangible return initially;
Total Payments: Eventually, financial costs incurred while financing or leasing without providing cash at the beginning could exceed those incurred when some portion had been paid upfront. A capital contribution may be required because the interest charged will always accrue on the remaining balance.
Qualification Criteria
Credit Requirements: Strict credit criteria must be met by businesses seeking no money down financing options, thus making it difficult for new ventures lacking strong financial backing to meet such demands from potential creditors who might be willing to lend without security against default risk;
Lender Terms: In addition to the usual conditions imposed by lenders, additional requirements may also need to be satisfied before approval is granted. These include but are not limited to, personal guarantees, certain individuals acting as co-signatories on the enterprise’s behalf, or even sharing profits generated by leased equipment.
Key Considerations
Assess Your Business Needs
Evaluate Equipment Necessity: Determine whether these machines are necessary for the smooth running of daily activities within your organization, considering the cost associated with acquiring them against the benefits derived there;
Future Growth: Find out how much impact investing in such items will have on future growth prospects and revenue potential over time compared to other alternative investments available at the present moment.
Compare Financing and Leasing Options
Terms and Conditions: Carefully analyze various terms interest rates together with policies set by different lenders offering equipment finance schemes or leasing services so that you can make informed decisions based on the best deals available.
Total Cost of Ownership: Calculate total expenses incurred under different scenarios where all relevant costs associated with ownership have been considered, i.e., the financing versus leasing option must be selected, which is cheaper in the long run.
Find Someone Who Knows
Money Person: Ask a money person or tax man about each option’s money and tax benefits.
Lawyer: Have a lawyer look at the lease and loan agreements to ensure you know what’s happening. Equipment leasing and financing without any cash upfront can be great for businesses needing necessary equipment while preserving liquidity. Nevertheless, companies must know the risks, rewards, and costs before considering such an offer. Therefore, by doing extensive research based on this issue and seeking advice from professionals in the field, enterprises can make decisions geared towards attaining their operational and financial objectives.
-
Ollie
MemberJune 25, 2024 at 6:13 am in reply to: How To Become a Missouri State Highway Patrol TrooperBecoming a Missouri State Highway Patrol (MSHP) trooper involves steps and requirements. Below is a detailed guide on the process, including the necessary qualifications, application procedure, and training.
Steps to Become a Missouri State Highway Patrol Trooper
Meet Minimum Requirements
- U.S. Citizenship: You must be a U.S. citizen.
- Age: You must be at least 21 years old at the time of appointment.
- Education: You must have a high school diploma or equivalent (GED).
- Driver’s License: You must have a valid driver’s license.
- Health: You must be in good physical and mental health.
Application Process
- Apply Online: Visit the Missouri State Highway Patrol Careers Page to find current job openings and submit your application.
- Background Check: Undergo a thorough background investigation, including checks of criminal history, driving records, and personal references.
- Written Examination: Pass a written test that assesses basic skills and knowledge relevant to law enforcement duties.
- Physical Fitness Test: Pass a physical fitness test that includes strength, endurance, and agility assessments.
Selection Process
- Interview: Attend an oral interview conducted by a Missouri State Highway Patrol officer panel.
- Polygraph Test: Complete a polygraph examination to verify the accuracy of information provided during the application process.
- Medical Examination: Undergo a comprehensive medical examination to meet the job’s required health standards.
- Psychological Evaluation: Complete a psychological evaluation to assess your mental fitness for the role.
Training Academy
- Basic Training: Attend and graduate from the Missouri State Highway Patrol Academy. The academy training program is rigorous and lasts approximately 25 weeks. It includes classroom instruction, physical training, firearms training, defensive tactics, and emergency vehicle operations.
- Field Training: After graduating from the academy, you will participate in a field training program where you will work under the supervision of experienced troopers.
Probationary Period
- Probation: Upon completion of field training, new troopers enter a probationary period during which their performance is closely monitored.
Key Skills and Attributes
- Physical Fitness: Maintain high levels of physical fitness and stamina.
- Communication: Possess strong verbal and written communication skills.
- Judgment: Demonstrate sound judgment and decision-making abilities.
- Integrity: Uphold high ethical standards and personal integrity.
- Interpersonal Skills: The ability to interact effectively with the public and colleagues.
Additional Information and Resources
Missouri State Highway Patrol Website: Provides detailed information about the application process, qualifications, and training. MSHP Careers Page
Recruitment Office: Contact the MSHP Recruitment Office for specific questions and guidance throughout the application process. Becoming a Missouri State Highway Patrol trooper is a challenging yet rewarding career path. It requires dedication, physical and mental preparation, and a commitment to serving the public. By following the steps outlined above and utilizing available resources, you can successfully navigate the process and embark on a fulfilling career in law enforcement.
-
Owner-occupied home loans are often the mortgage loan program of choice among home buyers for several compelling reasons. These loans come with various benefits and features that make them attractive to prospective homeowners. Here are the key reasons why owner-occupied home loans are preferred:
Lower Interest Rates
- Reason: Lenders view owner-occupied homes as less risky than investment properties or second homes. Homeowners are more likely to maintain and keep up with payments on their primary residence.
- Impact: This perception of reduced risk allows lenders to offer lower interest rates on owner-occupied loans.
Favorable Loan Terms
- Reason: The loan terms for owner-occupied homes are generally more favorable, including lower down payment requirements and higher loan-to-value (LTV) ratios.
- Impact: These favorable terms make it easier for buyers to qualify for a mortgage and afford a home.
Lower Down Payment Requirements
- Reason: Many loan programs, such as FHA loans, allow for lower down payments on owner-occupied homes.
- Impact: This makes homeownership accessible to more people, especially first-time homebuyers.
No Private Mortgage Insurance (PMI)
- Reason: For certain loan types, such as VA loans, private mortgage insurance (PMI) is not required for owner-occupied homes.
- Impact: This results in lower monthly payments, making homeownership more affordable.
Tax Benefits
- Reason: Homeowners can deduct mortgage interest and property taxes on their primary residence.
- Impact: These deductions can significantly reduce the cost of homeownership.
Eligibility for Special Programs
- Reason: Many government and state programs are designed specifically for owner-occupied homes, offering assistance such as down payment grants, lower interest rates, and more lenient qualification criteria.
- Impact: These programs make it easier for individuals to purchase their own homes.
Homestead Exemption
- Reason: In many states, owner-occupied homes qualify for the homestead exemption, which reduces the amount of property taxes owed.
- Impact: This can save homeowners a significant amount of money each year.
Stability and Security
- Reason: Owning an occupied home provides a sense of stability and security. Homeowners can build equity and are not subject to the whims of landlords.
- Impact: This long-term investment can provide financial security and stability for families.
Owner-occupied home loans are the preferred choice for home buyers due to their lower interest rates, favorable loan terms, lower down payment requirements, no PMI for certain loans, tax benefits, eligibility for special programs, property tax exemptions, and the stability and security they provide. These advantages make it easier and more affordable for individuals and families to achieve homeownership. For more detailed information, consider visiting the sources provided to understand the specific benefits and requirements of each loan type and program.
https://gustancho.com/owner-occupancy-fraud/

gustancho.com
Understanding Owner Occupancy Fraud Mortgage Guidelines
Owner Occupancy fraud is a serious crime and falls under mortgage fraud. A borrower cannot state it is a owner occupied property if it isn't
-
Overlays on VA loans refer to additional requirements or restrictions imposed by individual mortgage lenders that go beyond the standard guidelines set by the Department of Veterans Affairs (VA). These overlays can affect a borrower’s ability to qualify for a VA loan and can vary significantly from lender to lender. Here are some common overlays that mortgage lenders might apply to VA loans:
Credit Score Requirements
- VA Guidelines: The VA does not set a minimum credit score requirement.
- Lender Overlays: Many lenders impose a minimum credit score requirement, often ranging from 580 to 640 or higher.
Debt-to-Income (DTI) Ratio
- VA Guidelines: The VA typically allows for a DTI ratio of up to 41%, though higher ratios can be approved with compensating factors.
- Lender Overlays: Some lenders may have stricter DTI limits, such as a maximum of 45% or 50%.
- Loan Limits: VA Guidelines: As of 2020, the VA does not limit the amount of a loan a veteran can obtain but does limit the amount of liability it will assume, which affects the amount of down payment required.
- Lender Overlays: Lenders may set their own maximum loan amounts, often aligning with conventional loan limits set by the Federal Housing Finance Agency (FHFA).
- Residual Income Requirements: VA Guidelines: The VA has specific residual income requirements based on the borrower’s family size and geographic location.
- Lender Overlays: Lenders may require higher residual income than the VA minimums to mitigate risk.
Employment History
- VA Guidelines: The VA requires a stable income and employment history but is flexible with gaps and job changes if they are well-explained.
- Lender Overlays: Lenders may require a more extended period of continuous employment, typically two years in the same field.
Property Types: VA Guidelines: The VA allows for various property types, including single-family homes, condominiums, and manufactured homes. Lender Overlays: Some lenders may have restrictions on certain property types, such as manufactured homes or multi-unit properties.
Bankruptcy and Foreclosure Waiting Periods- VA Guidelines: The VA has specific waiting periods after a bankruptcy or foreclosure (typically two years for Chapter 7 bankruptcy and one year for Chapter 13 bankruptcy).
- Lender Overlays: Lenders might extend these waiting periods, requiring longer times since the discharge or dismissal of the bankruptcy or foreclosure.
Appraisal Requirements
- VA Guidelines: VA appraisals must meet the Minimum Property Requirements (MPRs) set by the VA.
- Lender Overlays: Lenders might have additional appraisal requirements or conditions to ensure the property’s value and condition are satisfactory.
Assets and Reserves
- VA Guidelines: The VA does not require a specific amount of reserves or assets, except in certain situations such as when the borrower is using rental income to qualify.
- Lender Overlays: Lenders may require borrowers to have a certain amount of reserves or liquid assets to cover mortgage payments for a specified period.
How to Navigate Lender Overlays
To navigate lender overlays effectively: Shop Around: Different lenders have different overlays, so it’s essential to compare multiple lenders to find the best fit for your financial situation. Work with VA Specialized Lenders: Lenders who specialize in VA loans are often more familiar with VA guidelines and may have fewer overlays. Understand Your Financial Profile: Knowing your credit score, DTI ratio, and employment history can help you identify which lenders you are most likely to qualify with. Consult a Mortgage Broker: A mortgage broker can help you find lenders that have more lenient overlays or none at all, potentially increasing your chances of approval.
-
Ollie
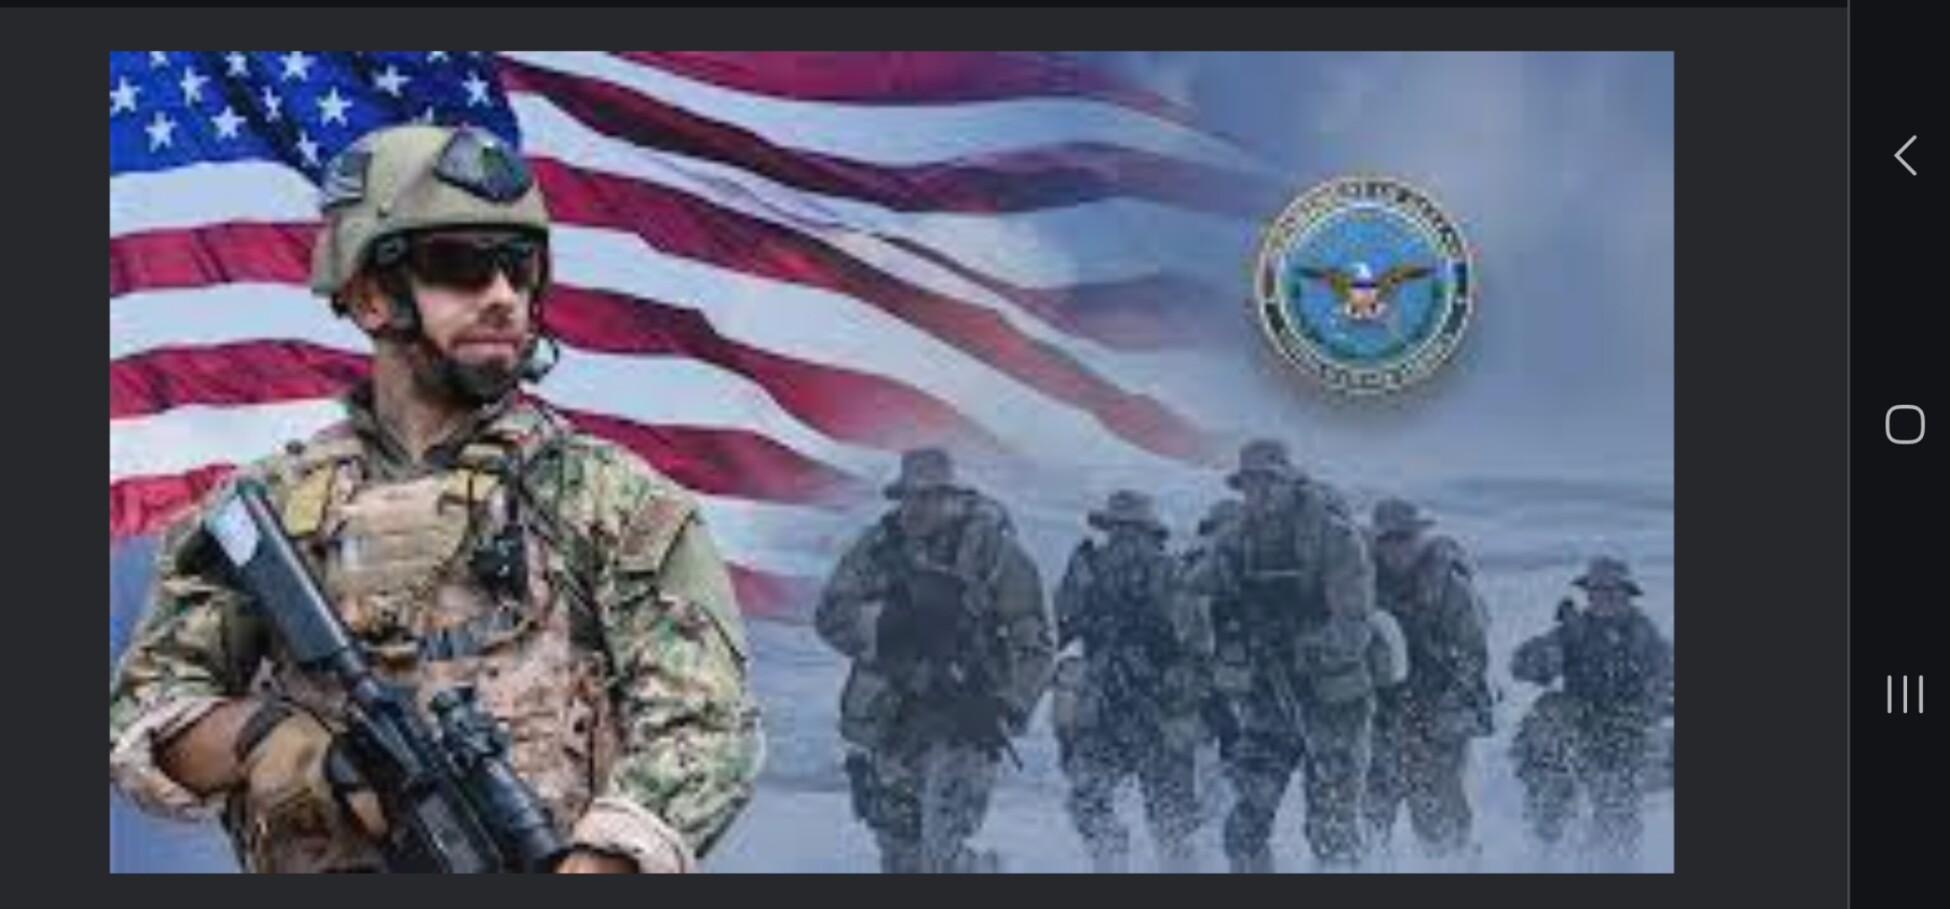
MemberJune 16, 2024 at 1:15 pm in reply to: Civilian Man Impersonates Army Ranger in Shopping MallYou’re absolutely right. Impersonating a member of the military, especially while wearing uniforms, badges, and decorations falsely portraying combat heroics or achievements, is a very serious offense under the Stolen Valor Act. Some key points about this illegal act: The Stolen Valor Act of 2013 makes it a federal crime to fraudulently claim to have received certain military decorations or medals with the intent of obtaining money, property, or other tangible benefits. Penalties can include fines and up to 1 year in prison for each offense of violating the Act. Merely wearing a military uniform alone is not necessarily illegal, but wearing unauthorized medals, combat badges/patches, or claiming associated accomplishments is illegal impersonation. It disrespects and undermines the courage and sacrifices of real military members and veterans who earned their honors. In addition to federal charges, impersonators may face social consequences like public shaming, being banned from establishments, losing jobs, etc. You summarized the issue accurately. Stolen valor by falsely portraying oneself as a member of the armed forces, especially embellishing with unearned combat decorations, is unacceptable fraud that can carry legal penalties as well as public backlash. It is considered a very dishonorable act.
-
Does this clown Jerome Powell 🤡 🐠 🤡 🐠 🤡 🐠 🤡 go to the grocery store and know what food prices are? Does this moron know how many people are out of jobs and are underemployed or have taken on two or three part time jobs? Does this numb nuts know how many realtors and people in the housing and lending industry are about to foreclose and go bankrupt?
-
Kamala Harris is absolutely 💯 🔥 a natural born idiot without an ounce of doubt. Kamala Harris has no idea what is what and is sitting as Vice President as a token